GPU开始金融化!黄仁勋拉上华尔街搞5000亿美元融资
Ranking
No observed public metrics; popularity remains neutral/archived.
Merged summary
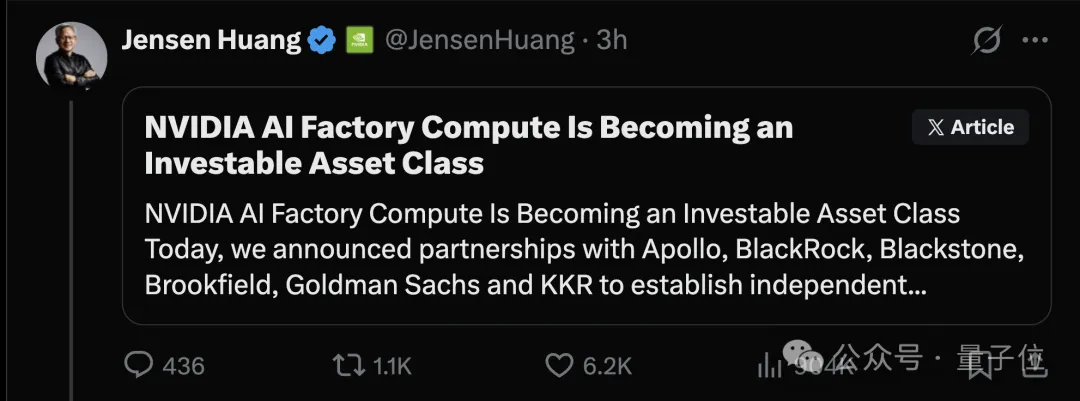
TL;DR - NVIDIA announced partnerships with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to build independent financing platforms targeting over $500B in third-party capital for AI data centers, reframing GPU compute ("AI factories") as an investable infrastructure asset class. It matters because it moves GPU buildout from corporate capex into credit/infrastructure markets, with attendant systemic risk.
- Jensen Huang's pitch: an AI factory (GPUs + networking + system software + CUDA + developer ecosystem) is fungible and redeployable across customers and clouds, so CUDA software upgrades extend useful economic life — citing A100 (2020) still in commercial use approaching a ~10-year economic life.
- Cited pricing as evidence of durable economics: H100 1-year lease ~$1.70/GPU-hr (Oct 2025) → ~$2.35 (Mar 2026); cross-vendor median on-demand ~$2.00 → ~$2.70 (Jun 2026); B200 cloud ~$5.30–7.05/GPU-hr.
- On circular-financing concerns: NVIDIA says it only provides the platform while lenders independently underwrite customer, demand, utilization, cash flow and residual value; NVIDIA may offer residual-value backstops covering up to 25% of a project.
- Skeptics' counterpoint noted in the article: SPV-style debt-funded buildouts push GPU risk into credit markets (NVIDIA CDS at highs), echoing dot-com vendor financing at Lucent/Nortel; Dwarkesh Patel's contrasting bull case argues compute stays scarce and commands a persistent premium.
Sources (1)
GPU开始金融化!黄仁勋拉上华尔街搞5000亿美元融资
TL;DR - NVIDIA announced partnerships with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to build independent financing platforms targeting over $500B in third-party capital for AI data centers, reframing GPU compute ("AI factories") as an investable infrastructure asset class. It matters because it moves GPU buildout from corporate capex into credit/infrastructure markets, with attendant systemic risk.
- Jensen Huang's pitch: an AI factory (GPUs + networking + system software + CUDA + developer ecosystem) is fungible and redeployable across customers and clouds, so CUDA software upgrades extend useful economic life — citing A100 (2020) still in commercial use approaching a ~10-year economic life.
- Cited pricing as evidence of durable economics: H100 1-year lease ~$1.70/GPU-hr (Oct 2025) → ~$2.35 (Mar 2026); cross-vendor median on-demand ~$2.00 → ~$2.70 (Jun 2026); B200 cloud ~$5.30–7.05/GPU-hr.
- On circular-financing concerns: NVIDIA says it only provides the platform while lenders independently underwrite customer, demand, utilization, cash flow and residual value; NVIDIA may offer residual-value backstops covering up to 25% of a project.
- Skeptics' counterpoint noted in the article: SPV-style debt-funded buildouts push GPU risk into credit markets (NVIDIA CDS at highs), echoing dot-com vendor financing at Lucent/Nortel; Dwarkesh Patel's contrasting bull case argues compute stays scarce and commands a persistent premium.